Airwallex Business vs Banxware
Side-by-side comparison — pricing, features, ratings, use cases. Find which Business Banking fits you best.
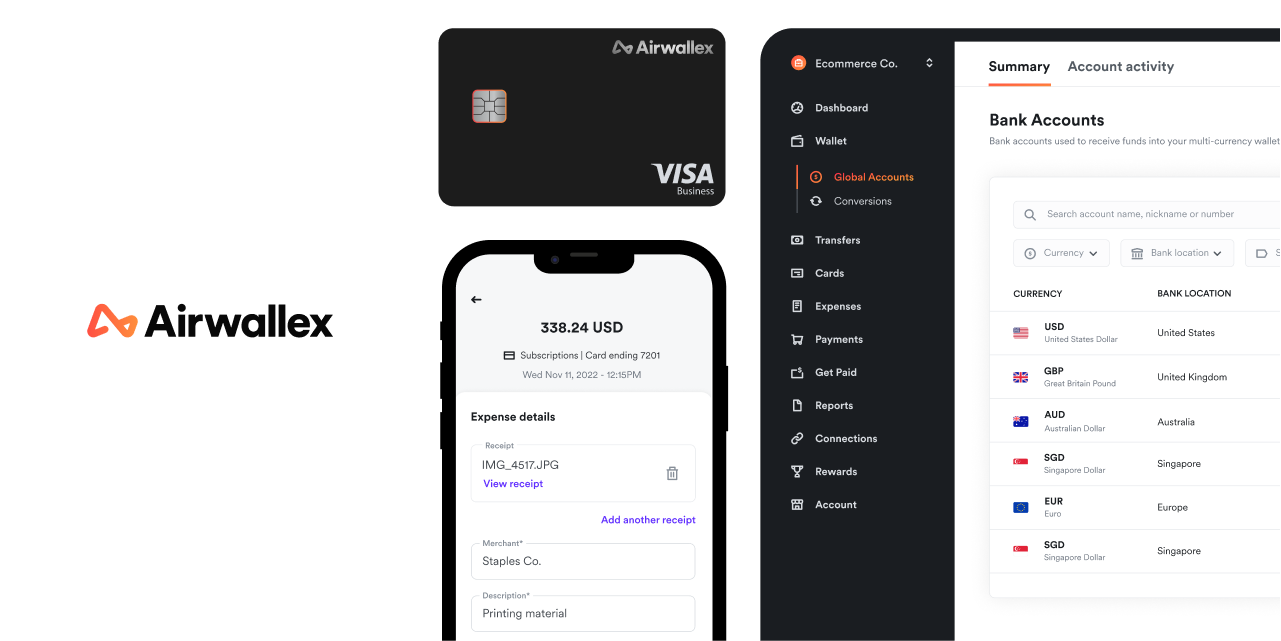
💰 Pricing
- No monthly account fee for Standard and Premium tiers (no paid subscription for the core account).
- International transfers using local rails are inexpensive; SWIFT payments may incur intermediary bank fees.
- FX conversion fee: typically 0.5% above interbank for Standard; can be reduced to 0.2% or lower in Premium/Enterprise plans.
- Card fees: virtual card is free; physical card issuance fee $10 per card (one-time). Card transaction fees: 0% for USD transactions, 0.5% for non-USD foreign exchange conversion.
- Cash deposit fee: 0.5% of the deposit amount (minimum $5, no maximum) when depositing into USD, AUD, or GBP accounts via local bank transfer.
- SWIFT transfer receiving fees: if you receive SWIFT payments, Airwallex may not charge, but intermediary banks may deduct $10-$30 from the amount.
- Currency conversion spread: Airwallex quotes 'interbank rate' but adds a conversion fee on top; fee varies and may be higher than advertised for less common currencies.
- Physical card replacement: issuing a new physical card will incur a $10 fee each time.
- Potential monthly maintenance fee for inactive accounts: check terms; not widely disclosed but may apply after extended inactivity.
🔧 Features
📋 Assessment
💪 Strengths
- Airwallex provides true multi-currency accounts with local receiving details in major markets like the US, UK, Europe, Australia, and Hong Kong. This means you can receive payments in local currencies without cross-border fees, making collections from overseas customers faster and cheaper. For example, a US-based company can get a local US account number for its UK entity, avoiding international wire fees for UK customers.
- The exchange rates are highly competitive. Airwallex uses interbank rates plus a small margin (often as low as 0.5% above the mid-market). This is significantly cheaper than most traditional banks, which can add 2-3% margins. For a business paying $500,000 in invoices annually, the savings can easily be in the thousands of dollars.
- The corporate cards (both virtual and physical) are a standout feature. They come with excellent expense management tools: you can set per-card spending limits, restrict them to specific categories (like travel or software), and track receipts in real-time. This gives finance teams granular control over employee spending, reducing the risk of fraud and simplifying reconciliation.
- Airwallex integrates seamlessly with major accounting platforms like Xero, QuickBooks, and NetSuite. This automates the flow of transaction data into your books, eliminating manual data entry and reducing errors. The API also allows for custom integrations, which is a boon for companies with complex payment workflows.
- Setting up and using Airwallex is fast and intuitive. The onboarding is entirely digital and typically takes less than a day, compared to weeks for a traditional bank account. The dashboard is clean and user-friendly, and you can manage payments, view balances in multiple currencies, and download statements without any technical expertise.
⚠ Watch out for
- Airwallex is not a bank, and your funds are not protected by deposit insurance (like FDIC in the US or FSCS in the UK). This is a critical distinction. If Airwallex were to become insolvent, you could lose your money. While the company is well-funded and has a strong track record, this lack of insurance is a significant risk for businesses holding large balances.
- The eligibility criteria are restrictive. To open an account, you need a registered business and must provide extensive documentation. Also, availability varies by country — for example, not all features (like local receiving details) are offered in every currency, and some regions have limited card issuance. This can be a dealbreaker for businesses in less-served markets.
- Despite the claim of interbank rates, Airwallex applies a small FX margin that can vary. Also, there are fees for certain transactions — like urgent payments (KRW, INR, etc.) and sometimes for USD-to-USD conversions within different countries. For small, high-frequency payments, these fees can erode the cost advantage, making it less economical than a flat-fee alternative.
- The customer support, while generally responsive, is not available 24/7. For a business that operates globally, immediate help during non-business hours can be hard to get. There have been reports of delayed responses via email, and phone support is limited in some regions. But you have access to a comprehensive help center and 24/7 chat for urgent issues.
- The account approval process can be stringent and may require a video call or additional verification for some businesses. While this is good for compliance, it can slow down onboarding. Also, some users have reported holds on funds when they send to new beneficiaries, which can impact cash flow if not anticipated.
🎯 Best for
Online businesses, startups, and SMEs that need global multi-currency accounts, borderless cards, and cost-effective cross-border payments without maintaining traditional banking relationships in every country.
🚫 Who should skip
Solo consumers looking for a personal checking account, domestic-only businesses that never deal with overseas payments, or companies that require a regulated local bank with physical branches and full deposit insurance.
📚 Learning curve
Moderate — account registration and KYC approval take some document preparation, but once set up, transferring money and issuing cards are straightforward from the dashboard.
🧑⚖️ Verdict
Airwallex is a compelling choice for businesses that regularly operate across borders and want to cut down on FX costs and speed up international payments. It's not for everyone — if you're a solo entrepreneur with minimal cross-border needs, the complexity isn't worth it. But for growing companies

💰 Pricing
- Banxware does not publish standard pricing.
- Pricing is individually negotiated with each marketplace or platform partner.
- Revenue model typically includes a revenue share or per-loan origination fee, often structured as a percentage of loan volume or interest margin.
- Implementation and API integration costs may apply.
- Custom development or onboarding fees may be required but are not disclosed publicly.
- Revenue-sharing terms may vary significantly and only become clear during contract negotiation.
- Potential minimum volume commitments or early termination fees in partnership agreements.
🔧 Features
📋 Assessment
💪 Strengths
- API-first architecture: Banxware is built for developers. Its API-first design means that integration is designed to be straightforward, allowing a platform's engineering team to embed the lending interface within days or weeks, not months. This minimizes friction and costs, which is crucial for tech-savvy platforms that want to move quickly and avoid a lengthy development cycle. The benefit is that it feels native to the existing user experience, reducing churn.
- Real transaction data underwriting: Banxware leverages the platform's existing data on its sellers—sales revenue, order volumes, customer reviews, and returns—to inform lending decisions. This allows for a more accurate and fast assessment of a business's health than traditional credit scores. For a seller with a high but seasonal revenue, a bank might see risk, but Banxware sees a pattern and can offer a tailored credit line. This makes financing more accessible and relevant, and it's a major differentiator.
- German SME market expertise: Banxware is deeply rooted in the German SME ecosystem, meaning its lending products are designed to comply with German and EU financial regulations, such as the required licensing and consumer protection laws. This localized knowledge ensures that platforms partnering with Banxware won't face regulatory surprises. It also means the product is fine-tuned to the needs of German businesses, like the 'Handelsregister' and the specific uses of short-term credit for inventory or seasonal payments.
- Immediate term financing for platform partners: Banxware is not just about the end borrower; it offers a clear revenue sharing model for the platform (though details are kept confidential). This makes the value proposition for the platform clear: they can earn a commission on each loan while enhancing their stickiness. The platform becomes more than a market; it becomes a financial ally, which can be a data-driven relationship, encouraging sellers to stay and grow.
- Streamlined user experience: Because the lending is embedded, the seller can get a loan offer without leaving the platform's interface, without re-entering business data, and without manual approval forms. This 'in-context' financing is a modern, efficient approach that reduces abandonment rates. The end-user experience is so smooth it can feel like a feature of the platform itself, not a third-party service.
⚠ Watch out for
- Not a direct-to-consumer product: The most obvious limitation is that Banxware is not something a business owner can simply sign up for individually. They must be a user of a partner platform. If your business doesn't operate on a platform that offers Banxware's financing, you have no direct access. This means that small businesses without strong platform affiliations are left out, which is a significant constraint for many.
- Geographic focus: Banxware is essentially Germany-only. While it operates within the EU, its focus is on German marketplaces and SMEs, and it may not be optimized for the legal, tax, or cultural nuances of other countries. Any platform outside Germany (or the German-speaking regions) will need to assess whether Banxware can support their international expansion, which is a big question mark.
- Transparency of commercial terms: As is typical for B2B fintech, Banxware does not publish its pricing or commission structures. This creates a challenge for potential partners in comparing costs. You have to contact sales to get a quote, which can be a time-consuming process with no upfront price point. For smaller platforms, this lack of transparency can be a barrier, as the costs might be prohibitive, but you won't know until you invest in a sales call.
- Dependence on platform data quality: The effectiveness of Banxware's underwriting is directly tied to the quality and completeness of the data the partner platform provides. A platform with poor data governance or sparse transactional data may not be able to offer its users meaningful credit lines. This could lead to a frustrating experience for the end borrower, who sees the offer but gets a rejection or an unfairly low limit, which could damage the platform's trust.
🎯 Best for
German marketplaces and B2B platforms that want to add instant SME financing through an API without building their own lending and risk infrastructure.
🚫 Who should skip
Individual small business owners seeking direct loans, and non-German platforms looking for a ready-made global embedded lending solution.
📚 Learning curve
Moderate — the API integration is developer-friendly for platform teams, but understanding underwriting requirements, regulatory considerations, and commercial terms takes time.
🧑⚖️ Verdict
Banxware is an excellent choice for German marketplaces and B2B platforms looking to embed SME lending into their ecosystem, thanks to its API-first approach and data-driven underwriting. It is not a direct lending solution for individual businesses, and its regional focus limits its use internation
📊 Use Case Suitability
Higher score = better fit. Scores from editorial review.
🧭 Which One Should You Pick?
Choose Airwallex Business if...
- You are: Online businesses, startups, and SMEs that need global multi-currency accounts, borderless cards, and cost-effective cro
- 👍 True multi-currency business accounts with local receiving details in major markets like the US, UK,
- 👍 Competitive exchange rates with lower foreign-exchange costs than most traditional banks, especially
- 👍 Virtual and physical corporate cards with strong expense-management controls, spending limits, and r
- 💰 Free tier available
- ⚠ Trade-off: Airwallex is not a chartered bank, so funds are not covered by traditional depos
Choose Banxware if...
- You are: German marketplaces and B2B platforms that want to add instant SME financing through an API without building their own l
- 👍 API-first architecture makes it easier for marketplaces to embed lending directly into their existin
- 👍 Uses real platform transaction data for underwriting, enabling faster and more relevant financing de
- 👍 Designed specifically for the German SME market, which means regulatory and market fit are more like
- ⚠ Trade-off: Not a direct lending solution for individual business owners; small businesses m
❓ Frequently Asked Questions
Is Airwallex a bank?
Airwallex is a global payments and financial technology platform, not a bank. It provides multi-currency business accounts, cards, and payment services through regulated bank partners in each region. Funds are safeguarded, but you should check local terms for deposit insurance and protection details.
What fees does Airwallex charge if the account is free?
The standard account has no monthly subscription fee, but Airwallex makes money on FX conversion spreads, card payment fees, wire transfer fees, and some local receiving fees. The exact cost varies by currency, payment method, and your account tier.
Can I get physical and virtual business cards from Airwallex?
Yes, Airwallex offers both physical and virtual corporate cards in supported regions. Virtual cards can be issued instantly for online purchases and employee expense controls, while physical cards are available for daily spending and ATM use depending on your country.
Does Airwallex integrate with accounting tools like Xero and QuickBooks?
Yes, Airwallex has native integrations with Xero, QuickBooks, NetSuite, SAP, and many other accounting and ERP tools. It also offers a full public API if you need custom payment, treasury, or expense-management workflows.
🔗 More Business Banking Comparisons
🔀 Explore Alternatives
📧 Save this comparison
We'll email you a link to this comparison. No spam.